
BC Poker AML Policy
The BC Poker AML framework is designed to reduce money laundering, terrorist financing, fraud and misuse of payment systems. BCPoker applies identity checks, transaction reviews and risk-based controls across financial activity. The operator’s published information identifies Twocent Technology Ltd and refers to an Anjouan gaming licence.
AML procedures can involve automated monitoring and additional checks when activity requires closer examination. These measures apply to deposits, withdrawals and other financial transactions.
Regulatory Basis of the Programme
BCPoker states that its platform operates under an Anjouan Gaming Licence and that its regulatory framework includes anti-money-laundering requirements. Its legal documentation also identifies AML compliance as a reason for processing personal and financial information.
A risk-based approach allows the level of review to vary according to the customer or transaction.
Customer Due Diligence Measures
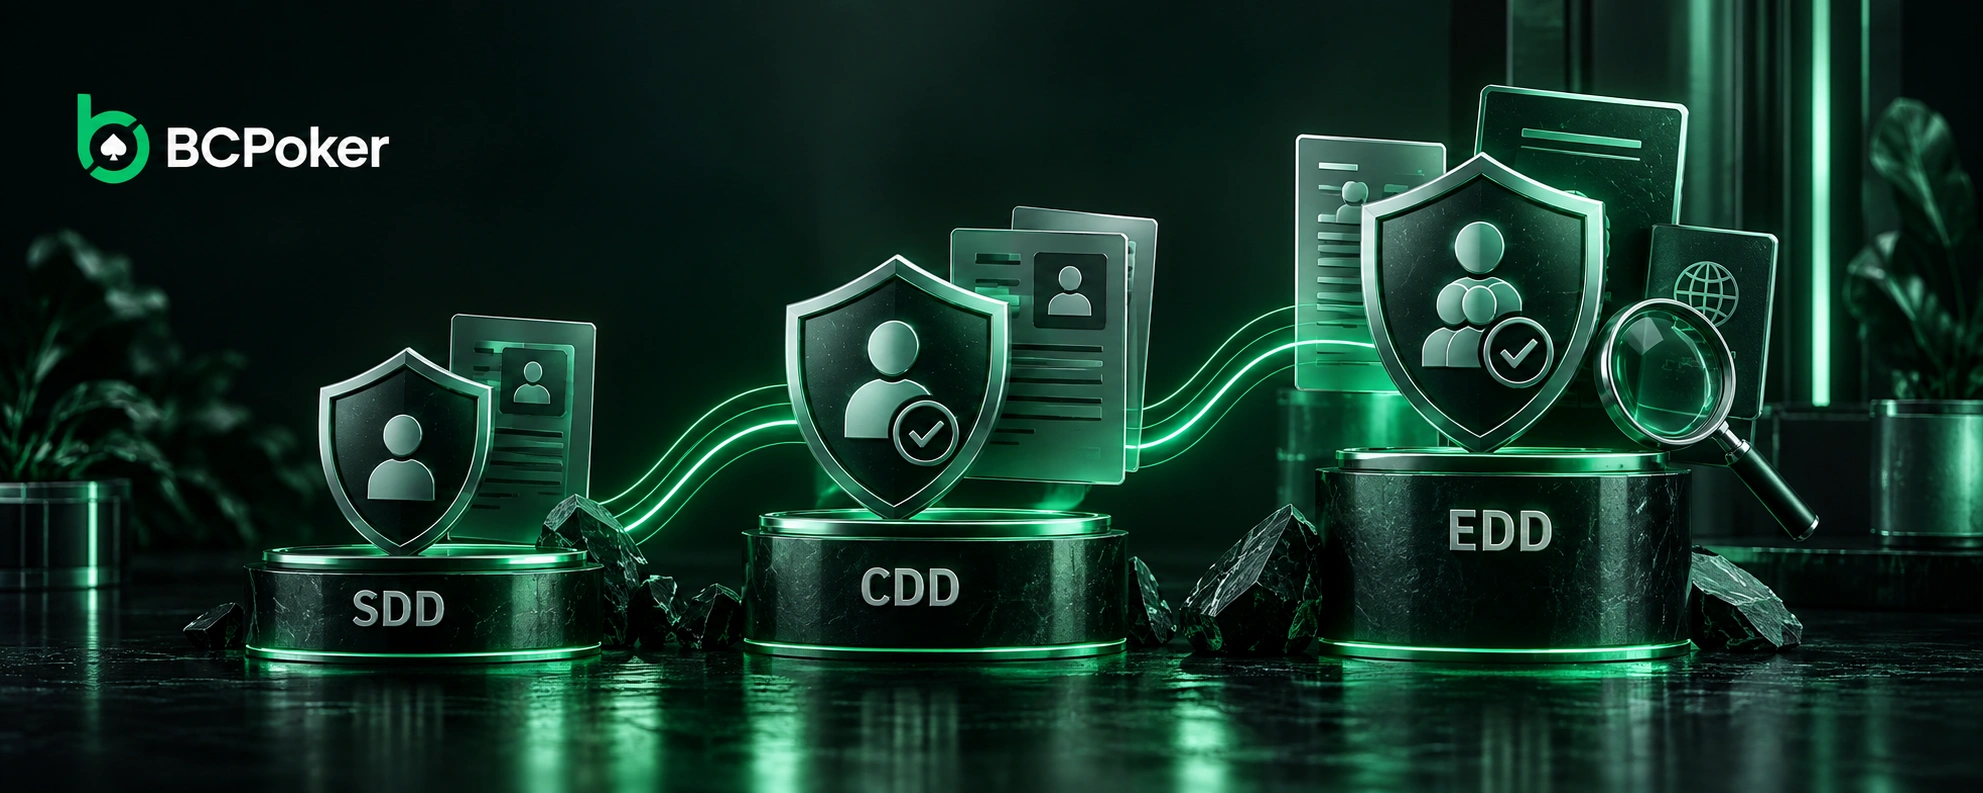
Customer Due Diligence helps establish who is using the service and whether the information provided is sufficient for compliance. BCPoker’s KYC policy describes three levels of review.
| Due diligence level | Typical application |
| Simplified Due Diligence | Extremely low-risk situations |
| Customer Due Diligence | Standard verification |
| Enhanced Due Diligence | Higher-risk customers or transactions |
Depending on the circumstances, users may be asked for an identity document, selfie or proof of address. Additional KYC information can be requested when identity or location needs to be established.
Transaction Monitoring and Risk Indicators
AML monitoring covers financial activity throughout the relationship with the platform. BCPoker states that transaction analysis, suspicious-activity monitoring and risk indicators support fraud prevention and compliance.
Reviews can consider transaction history and payment activity. Cryptocurrency transactions can also be assessed through available transaction records, while payment providers may participate in processing and verification.
Prohibited Practices and Blocked Jurisdictions
The AML framework is intended to prevent the platform from being used to move or conceal illicit funds. Activity that conflicts with compliance requirements can receive additional scrutiny.
Prohibited or restricted circumstances can include:
- Using payment methods that do not belong to the player.
- Concealing the source or ownership of funds.
- Providing false or misleading information.
- Conducting activity associated with restricted jurisdictions or prohibited sources.
- Attempting to bypass AML, KYC or transaction-monitoring controls.
BCPoker also restricts access from jurisdictions identified in its KYC requirements, including FATF-blacklisted countries and other prohibited locations.
Enhanced Checks and Account Restrictions
When a customer or transaction presents higher risk, BCPoker can apply enhanced due diligence and request further information, including identity documents, payment evidence or transaction explanations.
An unresolved review can affect withdrawals, payments or other services until the requested information has been assessed. Such a restriction does not necessarily mean prohibited activity has been confirmed; it can also remain while ownership or transaction details are examined.
Record Keeping and Reporting Duties
AML compliance depends on retaining records that support reviews of financial activity and verification decisions. BCPoker’s privacy policy states that transaction records may be retained for up to seven years for regulatory, legal and tax purposes, while certain fraud-prevention and security information can be retained for up to five years.
Personal and financial information may be shared with KYC providers, payment processors, infrastructure services and fraud-prevention partners where necessary for compliance or platform operations.